Who it's for
- Beneficiaries who want to pass an inheritance to children, grandchildren or a charity
- Families adjusting an estate after a death in England or Wales
- Take legal and tax advice before signing — the deed is binding and irrevocable
What's included
- About this template — what a deed of variation does and when to take advice
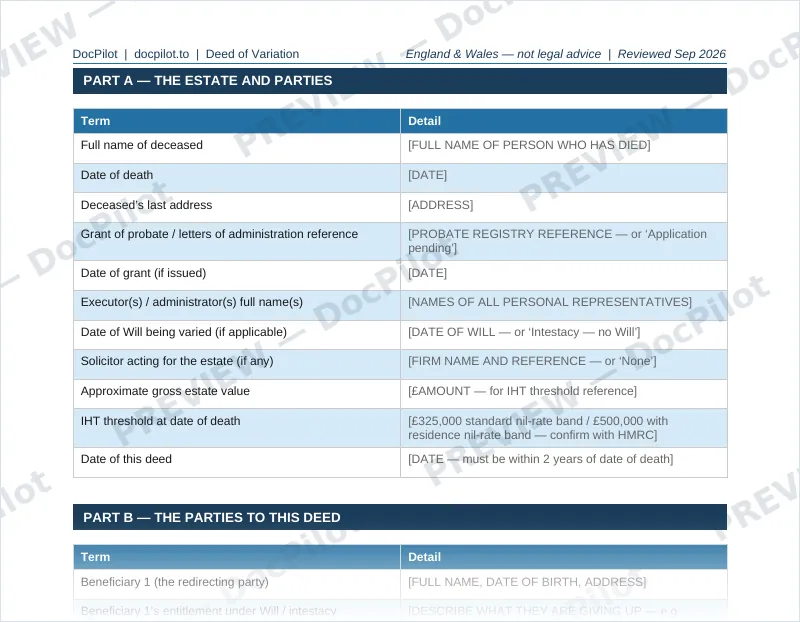
- Part A — The estate and parties: the deceased, grant, personal representatives, will date and estate value
- Part B — The parties to the deed: redirecting beneficiaries and the new beneficiary
- Part C — The deed (6 clauses): background, the variation, tax elections (IHT s.142 and CGT s.62(6)), no consideration, personal representatives, general
- Part D — Execution as a deed with witness blocks
Save with a bundle: get this plus 9 more documents in the Wills and Legal Bundle for £49.99.
See what's in the bundle →Key points covered
- Must be made within 2 years of the date of death
- Statements under s.142 IHTA 1984 and s.62(6) TCGA 1992 so the variation is read back to the date of death
- The redirecting beneficiary must receive nothing in return
- If the variation creates extra IHT, the personal representatives must notify HMRC within 6 months
- Each party signs in front of an independent witness
DocPilot templates are drafted from current legislation and official guidance (GOV.UK, legislation.gov.uk and the relevant regulators), checked against those sources and fully re-reviewed every six months. They are not legal advice. How we make our documents →
Read the guide
Related documents
Letter of Wishes£9.99 · See what's included →Executor's Checklist£14.99 · See what's included →Standard Will Template£19.99 · See what's included →
Questions
What is the time limit?
The deed must be made within 2 years of the date of death.
Do the executors need to sign?
Only if the variation creates extra inheritance tax, or if they are a party because administration is not complete. The template covers both.
Can I be paid for redirecting my inheritance?
No. A variation supported by payment or another benefit does not qualify for the tax treatment.
Should I take advice?
Yes. A deed of variation is irrevocable once signed, and the tax effects depend on the whole estate.
Deed of Variation
£19.99 · Word + PDF · instant download
Buy — £19.99 →Bought the wrong document by genuine mistake? Our Swap or Refund Promise lets you swap it or get a refund within 14 days.